Home health care is one of the most misunderstood terms in senior care, often confused with the non-medical help of in-home senior care. In reality, it’s a distinct, medical level of care: skilled, physician-ordered services delivered by licensed professionals, usually for a limited time. This guide covers what home health care includes, who qualifies, what Medicare and Medicaid pay for, and how to find a qualified agency.
What Is Home Health Care?
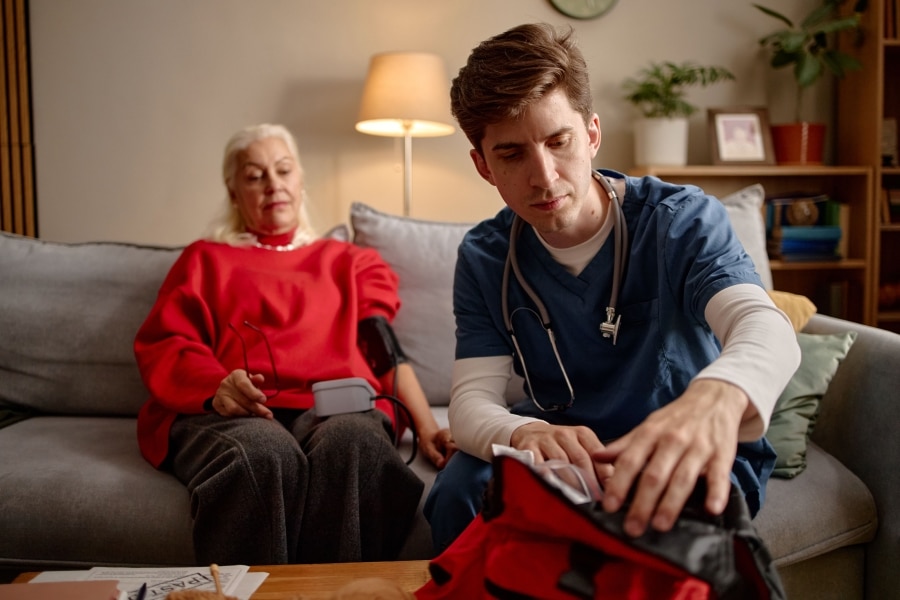
Home health care refers to skilled medical services delivered in a person’s home, ordered by a doctor and provided by licensed professionals, to help someone recover from an illness, injury, or surgery, or to manage a chronic condition. It’s typically short-term and intermittent rather than an ongoing daily service, and it’s aimed at improving or maintaining a specific health condition, not providing general daily assistance.
Home Health Care vs. In-Home Senior Care: What’s the Difference?
These two terms are often used interchangeably, but they describe different kinds of support. For a full look at non-medical in-home help, see Senioridy’s guide to in-home senior care. Here’s the practical distinction:
- Home health care is medical, delivered by licensed nurses and therapists, and ordered by a doctor as part of a formal care plan
- In-home senior care is non-medical, delivered by trained caregivers, and typically arranged directly by the family without a physician’s order
- Home health care is usually short-term and tied to a specific condition or recovery goal
- In-home senior care can continue indefinitely, as long as it’s needed
Many seniors use both at the same time: home health for the medical piece, personal or companion care for daily living support.
What Services Does Home Health Care Include?
According to Medicare’s coverage guidance, home health services can include:
- Intermittent skilled nursing care, such as wound care, injections, IV or nutrition therapy, and monitoring of an unstable condition
- Physical, occupational, and speech-language therapy (Senioridy’s guide to in-home physical therapy covers that service in more depth)
- Medical social services, such as help connecting to community resources
- Part-time home health aide care, when it’s provided alongside one of the skilled services above
- Medical supplies and durable medical equipment related to the plan of care
A home health aide’s help with bathing, dressing, or mobility is included, but only as part of a broader plan that also includes skilled nursing or therapy, not as a stand-alone service.
Who Qualifies for Home Health Care?
Per Medicare’s home health coverage guidance, qualifying generally requires meeting both of these conditions:
- Needing part-time or intermittent skilled nursing or therapy services, ordered by a doctor as part of a care plan
- Being considered homebound, meaning leaving home takes considerable effort or isn’t recommended because of a medical condition, even with help from a cane, walker, wheelchair, or another person
Being homebound doesn’t mean never leaving the house. Trips for medical care or short, infrequent outings, like attending a religious service, generally don’t affect eligibility. A doctor or other health care provider must assess the patient face-to-face and certify the need for home health services, and the care must come from a Medicare-certified home health agency.
Home health care is often needed after a hospital stay, when a senior returns home but still needs wound care, medication monitoring, or therapy to regain strength and mobility. Senioridy’s guide to post-hospital in-home care covers that transition in more detail.
Does Medicare Cover Home Health Care?
Generally, yes, when the eligibility criteria above are met. Per Medicare.gov, people pay nothing out of pocket for covered home health services. After the Part B deductible, a 20% coinsurance applies to covered durable medical equipment. Coverage isn’t capped at a set number of visits. In most cases, “part-time or intermittent” means up to 8 hours a day of combined skilled nursing and aide care, up to 28 hours a week, with short periods of more frequent care possible if a doctor determines it’s necessary.
Medicare does not cover:
- 24-hour-a-day care at home
- Home meal delivery
- Homemaker services, like shopping or cleaning, that aren’t related to the care plan
- Custodial or personal care, when that’s the only kind of help needed
Medicare Advantage plans must cover at least the same home health services as Original Medicare, though they may require using an in-network agency or getting prior authorization. A free SHIP counselor can help compare how a specific Medicare Advantage plan handles home health care.
Does Medicaid Cover Home Health Care?
Yes. Per Medicaid.gov, home health services are one of the mandatory Medicaid benefits that every state must cover for people who meet the state’s eligibility and medical necessity criteria, unlike some other home care benefits, such as personal care, which states can choose whether to offer. The specific amount, duration, and scope of covered home health services still vary by state, so a state Medicaid office or a local Area Agency on Aging is the best source for what’s covered locally and what the income and asset limits look like.
What Does Home Health Care Cost Without Full Coverage?
Because Medicare and Medicaid only cover home health care when someone meets the homebound and skilled-need criteria, families paying privately, filling a gap between what a plan approves and what’s needed, or supplementing skilled visits with additional support, typically face higher rates than personal or companion care, since skilled nursing and therapy require licensed professionals. For current benchmark rates by state, see Senioridy’s in-home care cost guide.
How to Choose a Home Health Agency
- Confirm the agency is Medicare-certified, which is required for Medicare or Medicaid to pay for services
- Use Medicare’s Care Compare tool to check quality ratings and patient experience data for agencies in a specific area
- Ask whether the agency has experience with the specific condition or recovery goal involved
- Ask what happens if the regular nurse or therapist is unavailable
- Confirm how the agency communicates with the patient’s doctor and how often the care plan is reviewed
Finding Home Health Care Near You
The Eldercare Locator, a public service of the Administration for Community Living, connects older adults and families with local Area Agencies on Aging, which can help identify home health agencies and other resources in a specific community. It can be reached online or by calling 1-800-677-1116.
Common Questions
Is home health care the same as personal or companion care?
No. Home health care is medical, delivered by licensed professionals, and ordered by a doctor. Personal and companion care are non-medical, delivered by trained caregivers, and typically arranged directly by the family.
How long does Medicare cover home health care?
For as long as a doctor continues to certify that the homebound and skilled-need criteria are met. There’s no set limit on the number of visits, though care is generally expected to be part-time or intermittent rather than continuous.
Can I choose my own home health agency?
Yes. A doctor or hospital discharge planner may recommend agencies, but the choice of which Medicare-certified agency to use belongs to the patient.
Whether home health care is arranged after a hospital stay or to manage an ongoing condition, the starting point is usually a conversation with a doctor about what level of care is actually needed. For families ready to compare local providers, Senioridy’s home health directory is a good place to start.
This article is for informational purposes only and does not constitute legal, financial, or medical advice. Program eligibility, coverage rules, and benefit amounts are subject to change and vary by state. Medicare Advantage plan benefits may differ from Original Medicare. For free, personalized Medicare guidance, contact your State Health Insurance Assistance Program (SHIP) counselor at shiphelp.org, available in every state at no cost. For decisions involving Medicaid eligibility or long-term care planning, families may want to consult a licensed elder law attorney or financial advisor, and for questions about a specific medical condition, consult the patient’s physician. Always confirm current requirements with official program representatives.